
CONVENTIONAL LOANS
A Flexible Path
To Homeownership
Conventional loans offer competitive rates, flexible options, and multiple paths to fit your goals - whether you’re buying, moving, refinancing, or investing.
Key Benefits
WHY CHOOSE A CONVENTIONAL LOAN
Competitive Financing
Conventional loans offer competitive financing options for qualified borrowers.
PMI Can Be Removed
PMI may be eligible for cancellation as you build equity in your home.
Flexible Options
Primary homes, second homes, and eligible investment properties.
More Property Choices
Available for eligible single-family homes, condos, and 2–4 unit properties.
Down Payment Options
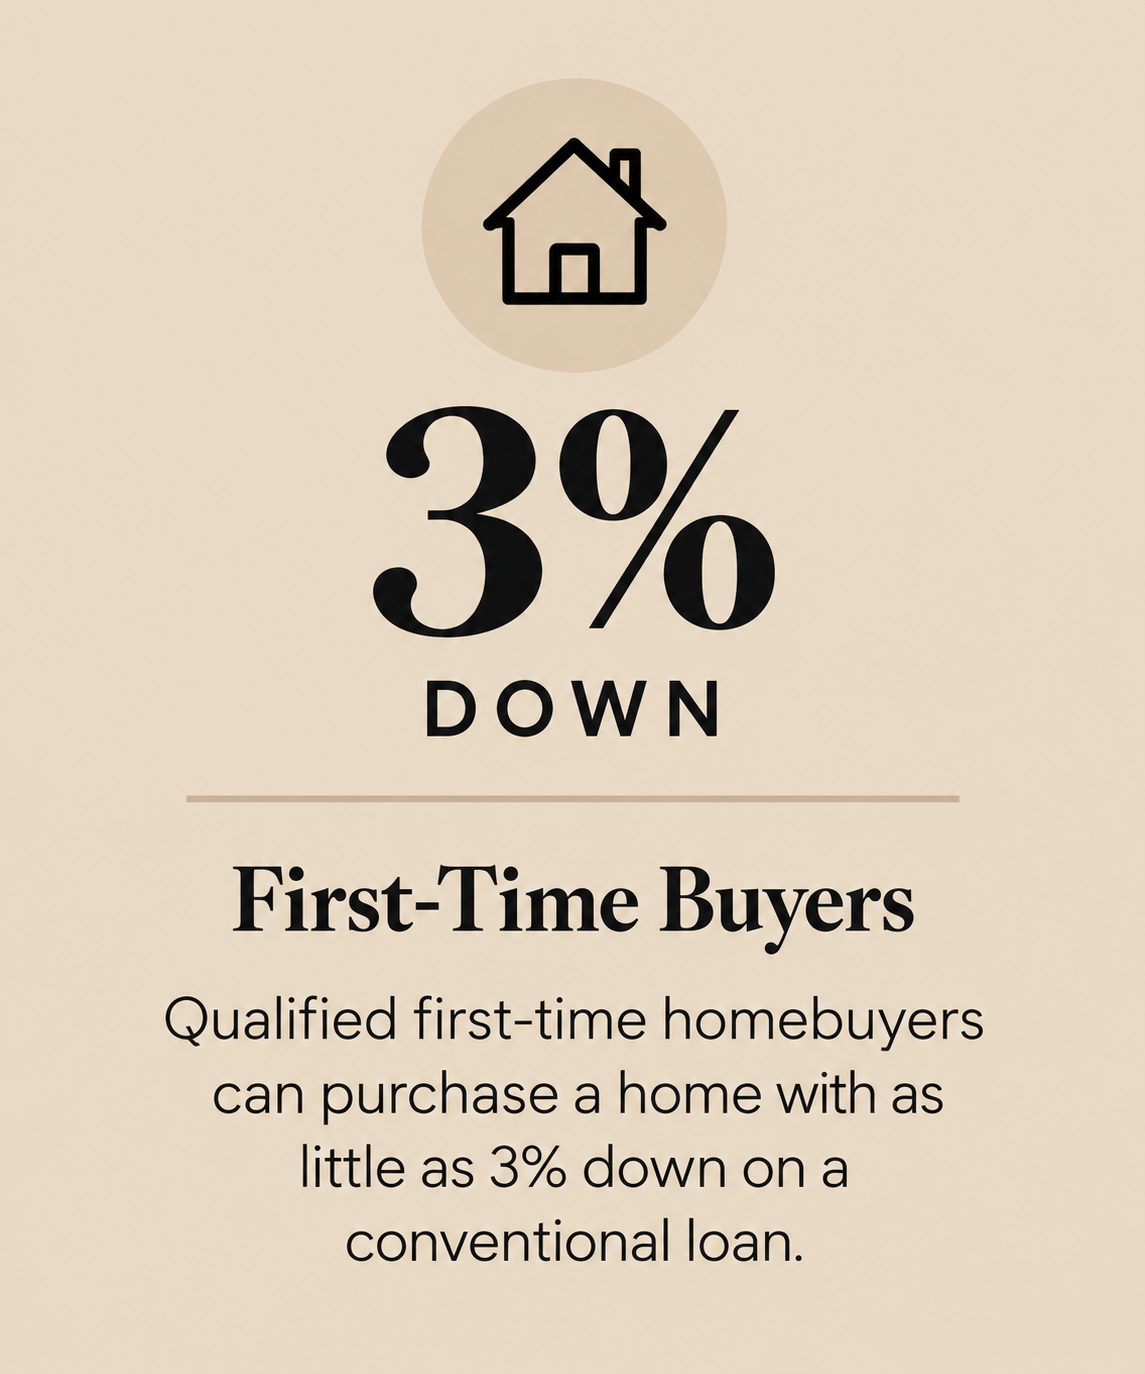
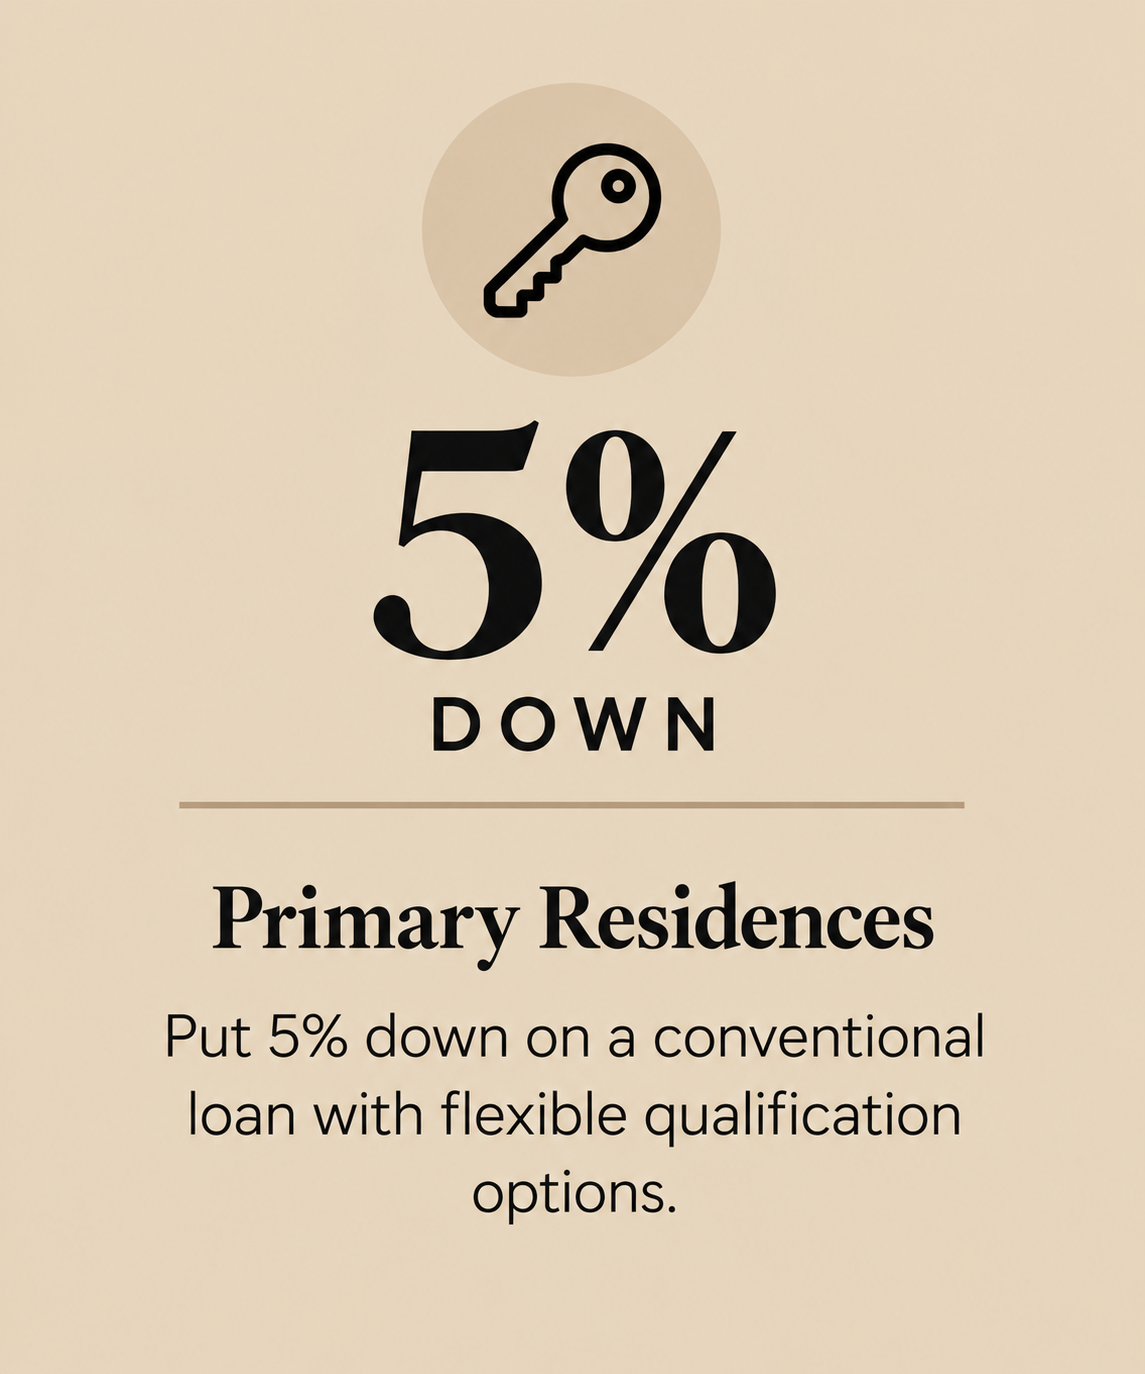
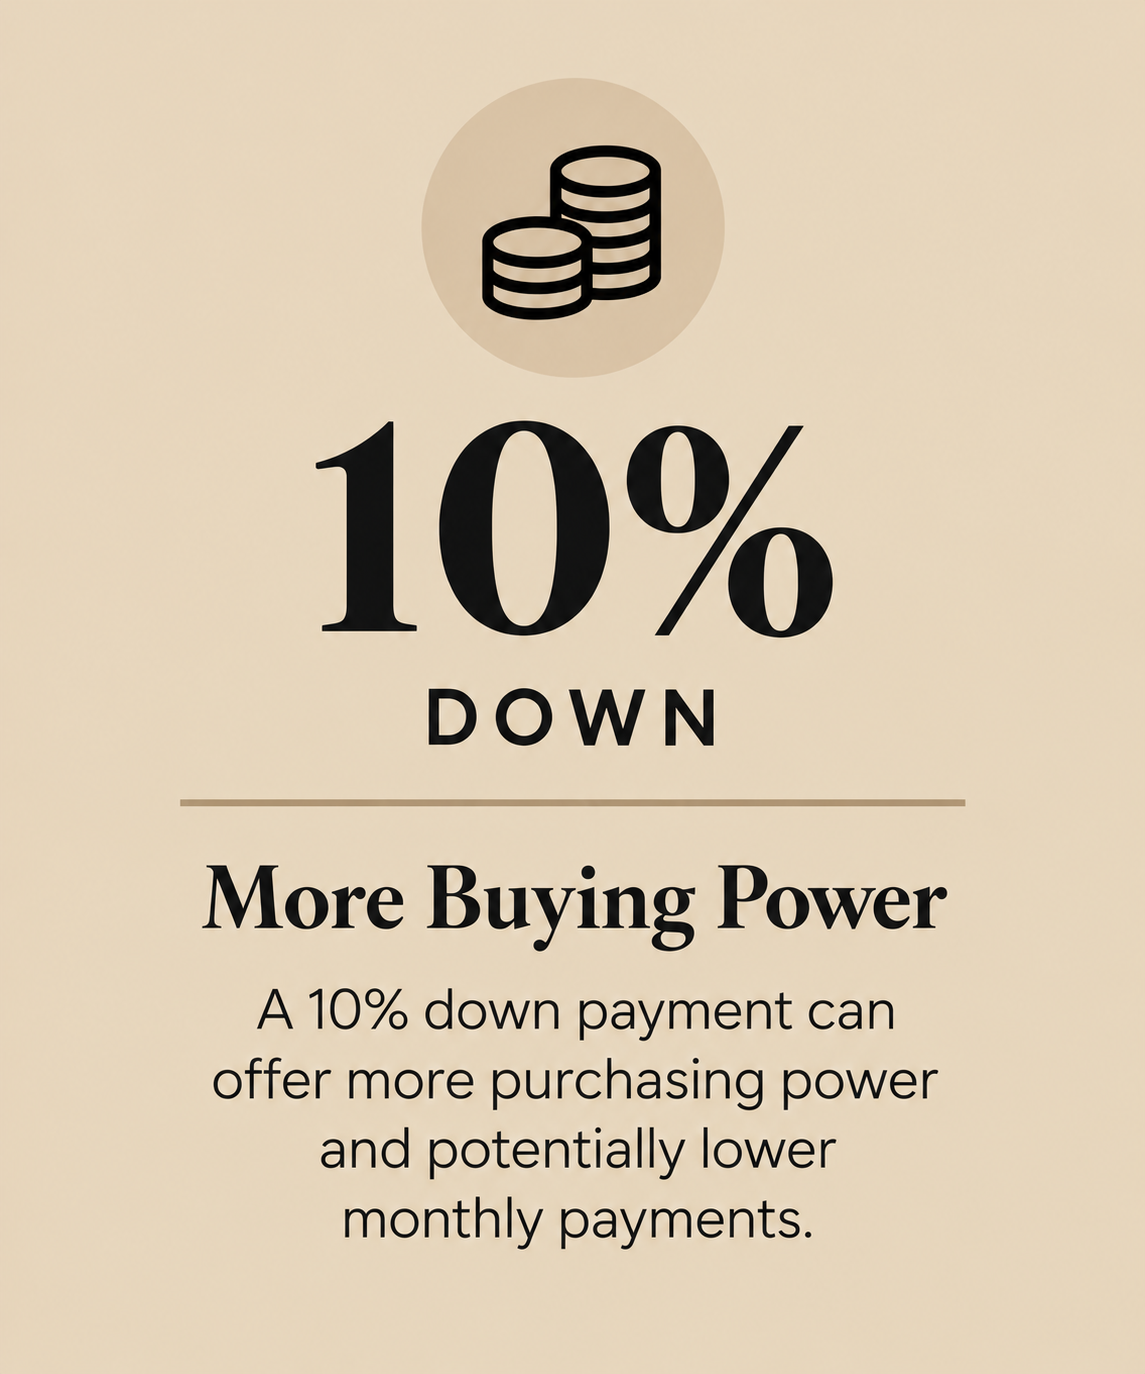
BUY A HOME WITH AS LITTLE AS 3% DOWN
CONVENTIONAL LOAN REQUIREMENTS
A QUICK LOOK AT THE KEY GUIDELINES
-
620+ Typical Minimum
A 620 credit score is generally the minimum for standard conventional financing. Higher credit scores may provide access to better interest rates, lower PMI, and improved loan pricing.
-
Up to 50% in Some Cases
Your debt-to-income ratio (DTI) measures your monthly debt obligations compared with your qualifying monthly income. Automated underwriting may allow a DTI as high as 50% depending on the overall strength of the loan file.
-
Up to 3%–9%
• Less than 10% down: Up to 3%
• 10%–24.99% down: Up to 6%
• 25%+ down: Up to 9%
• Investment properties: Up to 2%
Seller concessions can help cover eligible closing costs.
-
Flexible Property Options
Conventional financing may be available for eligible primary residences, second homes, investment properties, condos, and 1–4 unit properties.
-
Eligible gift funds may be used toward your down payment and closing costs. Documentation of the gift and source of funds may be required.
READY TO GET STARTED?
Explore Your Conventional Loan Options
Whether you’re buying your first home, moving, refinancing, or investing, we’ll help you find the right solution for your goals.